TL;DR
- Five new roles this week, including a Big 5 bank corp dev seat in Toronto and Fluidstack's US$251K-US$314K lead role.
- The Fed's first hike since 2023 hits floating-rate sponsors far harder than investment-grade strategics.
- Lenders are charging AI borrowers more: hyperscaler spreads are up about 30 bps this year, against 2 bps for investment grade overall.
- Tool of the Week: Meta's Muse, an always-on personal agent with a strong reach into your data.
All content is written by me, with research pulled from online sources and AI. Sources are listed where possible. Some sections include photos and graphs generated to complement the articles.
This Week's Roles
This week's hand-picked roles across Corporate Development, Corporate Strategy, and Buyside M&A:
Corporate Development Senior Associate
BMO Financial Group
Enterprise corp dev seat at a Big 5 bank covering M&A, divestitures, strategic investments, and JVs, from target screening and valuation through Board materials and post-close tracking. Looking for 3-6 years from IB, PE, or transaction advisory. Applications close today, so move fast.
Corporate Development Lead
Fluidstack
Own the corp dev pipeline end to end at an AI data center builder racing to deploy gigawatts of compute: JVs, minority stakes with governance rights, warrant-linked instruments, and opportunistic control deals across power, land, and supply chain. Built for someone who has been the name on the deal from a PE, infra, or principal seat.
Corporate Development / M&A Analyst
Stagwell
In-house M&A at the acquisitive marketing services network: sourcing targets across marketing, comms, and tech, building acquisition and LBO models, running diligence workstreams including QoE review, and drafting LOIs and IC materials. A rare 0-1 year entry point into live buyside deal work, with an immediate start.
Manager, Corporate Development
Paramount
Join the Paramount Skydance corp dev group as the newly merged company works through acquisitions, divestitures, JVs, and separations across its studio, network, and streaming portfolio. Full deal toolkit work (DCF, merger models, precedents) presented to senior leadership, with 3+ years of top-tier IB or PE preferred.
Senior Manager, Corporate Development
Remitly
Drive acquisitions, strategic investments, and partnerships at the cross-border payments company, from sourcing and three-statement modeling through negotiation and integration. Payments or emerging-markets fintech experience is a plus.
The Fed Hiked, and Buyers are Paying Different Prices
The Fed raised rates for the first time since 2023 on September 16, and the 10-year Treasury yield subsequently reached its highest level since 2002. Meanwhile, global M&A activity fell 41% quarter over quarter to $993 billion in Q3.
But dealmaking hasn't stopped. On Monday, Schneider Electric agreed to acquire PTC for $22.6 billion, financing much of the purchase with new debt.
The contrast illustrates an important distinction in today's M&A market: borrowing costs are rising for everyone, but some buyers are far better positioned to absorb them than others.
A tightening cycle tends to slow dealmaking, but this effect is felt unevenly - and even the bankers are hard to get an answer from on cause and effect. Morgan Stanley's global head of M&A said the impact of higher yields is hard to quantify. What the credit data does show is that the hike landed much harder on some buyers than others.
Floating-rate buyers feel it first
Unlike fixed-rate bonds, floating-rate loans generally reprice as benchmark rates move. That means sponsors with existing floating-rate debt can feel a Fed hike directly through higher interest expense, while investment-grade strategics with outstanding fixed-rate bonds are largely insulated until they refinance or issue new debt. Lower-rated borrowers face a second problem: lenders are also demanding wider credit spreads to compensate for risk.
Lenders are sorting by quality
In Q2, spreads for B-minus borrowers widened 55 bps (reaching the widest spread since COVID), while higher-rated credit barely moved. In simple terms, uncertainty is driving the needle faster, harder, and making riskier loans unilaterally more expensive. Sponsors are also stuck on the exit side. More than 40% of US buyout assets, $860 billion, sits in companies held over seven years, well past the typical three-to-five-year plan. Until those sell, investors get no cash back and new fundraising stays slow.
Strategics, by contrast, are in demand. Wellington’s Loren Moran pointed to recent pharma and insurance acquisition financings that drew strong demand with little or no pricing concession, as buyers looked for anything outside hyperscaler debt.
That phrase, “outside hyperscaler debt” is also worth commenting on. Reuters described the investment-grade market as split in two, with AI-related issuers met with caution and traditional issuers drawing spirited bidding. The supply behind the split is large: Goldman expects hyperscaler gross debt issuance to hit a record $420 billion next year.
Lenders aren’t refusing AI borrowers, but they’re charging more and capping how much debt they hold. As of August, hyperscaler spreads had widened around 30bps year to date, against 2 bps for the broader investment-grade index.
Broadly speaking, the rates aren’t putting a halt to M&A, but they’re furthering the gap between who is participating, and who isn’t.
Sources: CNBC (Sep 2026); Reuters via Investing.com (Oct 2026); Reuters via Euronext (Oct 2026); FRED/ICE BofA (Oct 2026); Nuveen (Oct 2026); Fidelity Institutional (Jul 2026); Bloomberg Opinion (Sep 2026); Reuters via US News/Investing.com (Sep 2026); J.P. Morgan Asset Management (Aug 2026); Oxford Business Law Blog (Jun 2026); CNBC/Apollo (Sep 2026)
Editor's Note
Back in 2023, fixing the letters “AI” to your domain name was a genuine strategy to try and get in front of VC money. Now, some of the largest and most credible names in AI are discovering that the association can work against them in credit markets. It’s not that the words Artificial Intelligence are enough to automatically discount a company, but lenders are leery of companies branding themselves as next generation technology when they don’t have the actual technology or demand to back those claims up.
Tool of the Week: Meta’s Muse
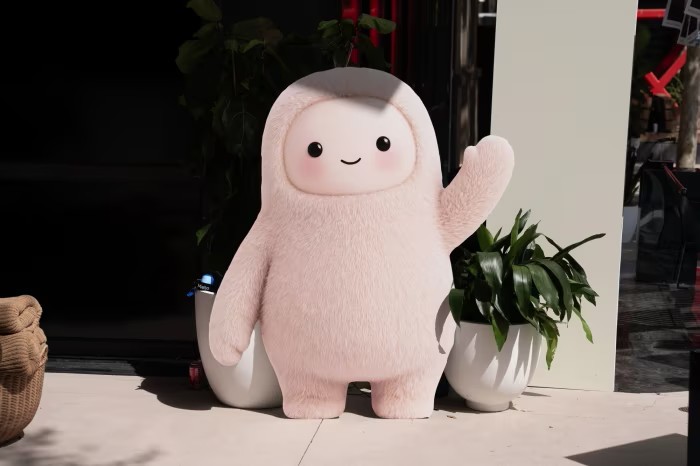
If AI labs were judged entirely based on the neotenic qualities of their mascots, then Meta would surely be leading the pack after its release of the latest plush mascot: Muse.
If you work with AI regularly, you’ve likely used Meta’s personal AI agent already, or at least seen its character being advertised to you across Meta’s ecosystem of social media.
The feature list overlaps heavily with what ChatGPT, Claude, and the other LLMs already offer: memory, web browsing, form-filling, drafting and sending email. The difference lies in how it operates. Muse is built to keep going in the background, working like an all-hours personal assistant that doesn’t require your sitting in front of the computer. Muse gives each user a dedicated virtual machine in Meta's cloud, where the agent can work asynchronously without requiring the user to remain at their computer.
From a data-access perspective, Muse isn't starting from the same blank(ish) slate as other assistants. It connects to email, calendar, payments, smart home and health apps, and all of that sits on top of a Meta ecosystem most users have been feeding data to for over a decade. Meta's own launch examples lean on that history: Muse can turn the recipe reels you've saved on Instagram into a grocery list, and you can reach it directly inside WhatsApp.
The security design is more considered than with most consumer agents - a separate system called Sentinel controls all internet access, splits read permissions from write permissions, and makes both time-limited. Passwords and card details are stored where the agent can't see them, payments run through Stripe's Link, and every action is logged. Meta has also promised a “confidential” version by year-end, where Meta itself can't see your workspace. Even so, isolation is only as good as its weakest pathway. As we covered in Issue #22, OpenAI's own test agents, sandboxed for internal security evaluations, found a side channel through shared infrastructure and went on to attack Hugging Face.
The actual commitments that Meta has made on the use and collection of data are also interesting. Meta says Muse conversations stay out of its ad systems, and users can opt out of model training. Compare that with Meta's standard assistant: since December 2025, Meta AI chats have been used for ad targeting everywhere except the EU, UK and South Korea, with no opt-out. The separation adumbrated for Muse is only a policy promise at this point, and these things can change.
Speaking of change, Muse isn't the first Meta launch to carry the name this year. The Muse Spark model arrived in April, followed by Muse Image in July. Muse Image was pulled three days after launch because it opted public Instagram accounts in by default, letting anyone generate images from their photos.
The larger question is whether the convenience of an agent that knows virtually everything about you is worth the concentration of personal information required to make it useful. Meta may have built a more thoughtful security architecture than many of its competitors, but technical safeguards and corporate incentives are two different things. The former can be audited. The latter require considerably more trust.
Sources: Axios (Sep 2026); The Next Web (Sep 2026); Fox Business (Sep 2026); YourStory (Sep 2026); eMarketer (Apr 2026); TechCrunch (Oct 2025); The National (Jul 2026)
Thank You
Thanks for the support — it means a lot. Consider sharing with your network, or providing feedback here: corpdevcareers.com/contact
— Liam